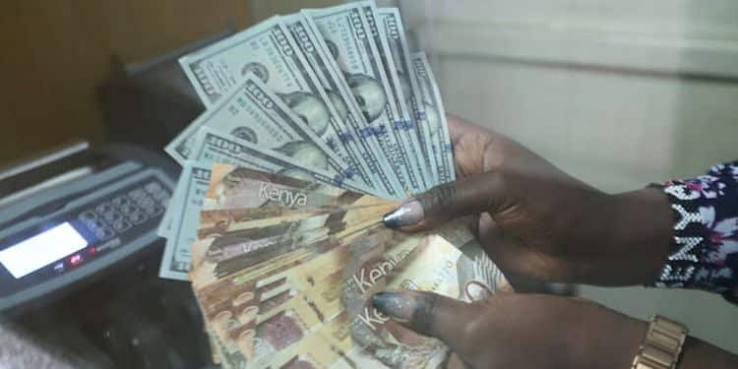
Kenya’s digital lending market is expanding rapidly, with outstanding loans reaching KSh153.8 billion by June 2026 as millions of borrowers increasingly turn to mobile platforms for emergency cash, school fees and business working capital.
The figure represents a 39.6 per cent increase from KSh110.1 billion recorded in December 2025, according to data from the Central Bank of Kenya (CBK). Digital credit providers advanced an additional KSh43.7 billion in the six-month period, underscoring the growing role of mobile loans in financing household and business needs.
The number of people borrowing from licensed digital credit providers rose by 32 per cent to 8.9 million from 6.74 million over the same period. The average loan size also increased to KSh17,280 from KSh16,335, suggesting that digital borrowing is extending beyond customers seeking only the smallest emergency advances.
The expansion has been supported by the growing number of licensed lenders, which reached 281 by September 2026. Their platforms allow customers to access credit through mobile applications and other digital channels without the paperwork and branch visits traditionally associated with bank loans.
However, the CBK has warned that most digital loans remain below KSh20,000 and have repayment periods ranging from one week to two months. While the facilities can help households meet urgent expenses and small businesses finance stock, the regulator says they are generally too small to support investments capable of significantly improving borrowers’ long-term earnings.
A survey by digital lender Tala found that approximately 45 per cent of borrowers used loans to stock their businesses, while 37 per cent borrowed to pay school fees and 23 per cent used the money to meet daily needs.
The convenience comes at a price. Digital lenders have been reported to charge daily flat rates of approximately 0.6 per cent, considerably higher than the average interest rates charged by commercial banks. The short repayment periods can also leave borrowers struggling to clear their balances, particularly when they rely on fresh loans to meet existing obligations.
The CBK has warned that the cost of recovering some small loans can exceed the amount advanced, discouraging lenders from pursuing repayment and potentially entrenching delinquency in the financial system.
Household debt pressures are also becoming more pronounced. Data from the FinAccess Household Survey showed that the proportion of Kenyan households experiencing debt distress rose to 16.6 per cent from 10.3 per cent in 2021.
The regulator is considering tighter safeguards, including proposals to stop lenders from automatically increasing customers’ borrowing limits after successful repayment. Instead, providers would be required to reassess borrowers’ financial circumstances before approving higher limits.
Digital lending has expanded access to credit for people who may struggle to qualify for conventional bank loans. But the rapid growth presents a challenge for regulators: ensuring that convenient access to small loans does not translate into a cycle of expensive borrowing and mounting repayment obligations.