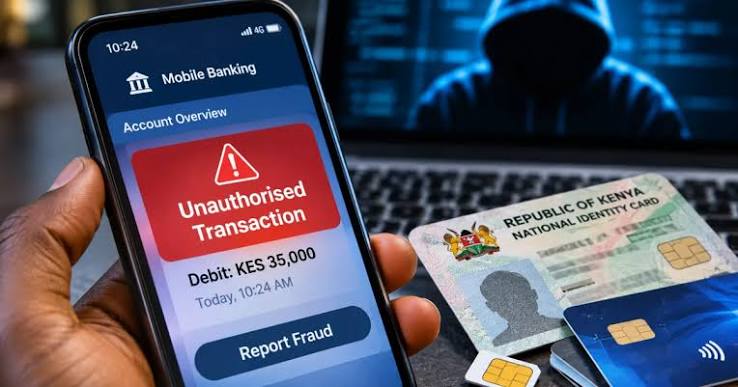
Identity theft concerns are growing in Kenya’s digital credit market, where 91 percent of people now borrow from digital lenders, according to Tala’s 2026 MoneyMarch report. TransUnion data show 4.5 percent of account creation attempts in Kenya were suspected of being fraudulent in 2025. Tala’s senior compliance and ethics manager, Tabby Mugechi, says lenders must strengthen customer verification.
Tala’s 2026 MoneyMarch report found that 91 percent of Kenyans borrow from digital credit providers, up from 87 percent a year earlier. Digital lenders have also overtaken chamas and family support as the first source of emergency funds, with 58 percent of Kenyans saying they had relied on digital loans to cover emergency expenses. The report was produced with TransUnion, Pezesha and the Centre for Investigation and Security Studies, although Tala, a lender, commissioned it.
The fraud figures point to a specific weakness. TransUnion data show that 4.5 percent of account creation attempts in Kenya were suspected of fraud in 2025. The initial sign-up process has been identified as the most vulnerable moment for identity theft, because a fraudster who passes it can open accounts in someone else’s name.
The risk is widespread across the public. A TransUnion consumer survey found that 81 percent of Kenyans reported being targeted by email, online, phone or text fraud in early 2025, compared with a global rate of 48 percent. Voice phishing was the most common method, reported by 46 percent of those targeted, followed by money and gift card scams.
Fraud is also rising in existing accounts. TransUnion reported that account takeovers rose 21 percent year on year in the first half of 2025. That pattern means lenders must protect accounts after sign-up as well as at the point of entry.
The regulatory framework is tightening. The Central Bank of Kenya approved 32 new digital credit providers in 2026, bringing the total to 259 by May. Digital credit providers must follow the Digital Credit Providers Regulations 2022 and the draft Non-Deposit Taking Credit Providers Regulations 2025 would require lenders to verify customers more rigorously.
Tala has responded by tightening its own checks. In May 2026, the company began requiring valid identification and a selfie from customers, which it says brings its procedures into line with the existing regulations and the proposed rules. Tabby Mugechi said completing the know-your-customer requirements was the simplest way for customers to protect their accounts.
The stakes are high for borrowers. When a fraudster opens a loan in someone’s name, the victim can be pursued for repayment and face damage to their credit record. Kenya’s Data Protection Act 2019 also requires lenders to protect the personal data they hold.
TransUnion’s latest regional work reflects the same concern. Its H1 2026 report found that security of personal data has overtaken product quality as the main factor African consumers weigh when choosing whom to deal with online. Trust, in other words, is becoming a competitive issue for lenders as well as a compliance one.
The next signals will be the finalisation of the draft lending regulations, TransUnion’s next fraud update and whether suspected fraud at account creation falls as identity checks tighten. Those measures will show whether faster digital lending can grow without leaving borrowers exposed.