Kenyan banks and payment companies have begun applying 16% value-added tax (VAT) to fees charged for processing digital payments, increasing costs for businesses that accept electronic transactions. At least one major commercial bank has notified customers that the charges will take effect on November 1, 2026, following changes introduced under the Finance Act 2026.
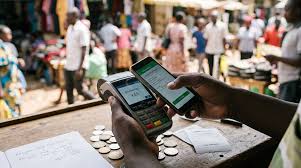
The tax covers fees earned by payment service providers for processing transactions, settling payments, connecting merchants to payment networks and operating payment gateways. Businesses using point-of-sale terminals, card machines, commercial Paybills and online payment platforms are among those likely to be affected.
The VAT is charged on the service fee rather than the total value of a transaction. For example, a merchant paying KSh350 in payment-processing fees would incur an additional KSh56 in VAT at the standard 16% rate, bringing the total charge to KSh406.
The change follows amendments to Kenya’s VAT framework that clarify the tax treatment of digital payment services supplied by payment service providers for a fee or commission. The Kenya Revenue Authority says the Finance Act 2026 amended the treatment of payment processing, settlement, merchant acquiring, gateway and aggregation services, bringing these services outside the exemption previously applicable to certain financial services.
The tax distinction is important for consumers and businesses. Ordinary person-to-person money transfers through mobile-money services such as M-Pesa and Airtel Money remain exempt, according to reports on the new measures. However, fees charged to businesses for receiving and processing card payments or using digital payment infrastructure are subject to VAT.
The additional expense could affect merchants already managing high operating costs. Businesses may choose to absorb the tax, reducing their margins, or pass some of the cost to customers through higher prices for goods and services.
The development also revives debate over the affordability of digital payments in Kenya, where electronic transactions are central to retail trade, online shopping and business-to-business payments. Industry stakeholders have previously warned that additional taxes on payment services could increase the cost of accepting electronic payments and discourage some smaller businesses from adopting them.
The new rules follow earlier legal disputes between the tax authority and payment companies over whether fees earned from digital payment processing qualified for VAT exemption. The Finance Act 2026 clarified the scope of the exemption, changing the tax treatment of services provided through digital platforms.
The implementation comes as the Central Bank of Kenya seeks to improve financial inclusion and reduce the cost of digital financial services. Businesses should review their bank and payment-provider fee schedules, while consumers should monitor whether merchants pass the additional costs on through pricing.
The extent of the impact will depend on how payment providers apply the tax and whether businesses absorb or transfer the extra expense. The key distinction remains that the 16% VAT applies to qualifying digital payment service fees, not automatically to the entire amount being transferred or paid.