SBM Bank Kenya has reported a 122 per cent increase in pre-tax profit to Sh911 million for the nine months to September 2026, up from Sh411 million recorded during the corresponding period last year, following growth in income and improvements in credit management.
The bank’s total income rose by 33 per cent to Sh5.44 billion, while operating profit increased by 197 per cent to Sh1.3 billion, reflecting stronger financial performance during the period.
Customer deposits grew by 29 per cent to Sh97.3 billion, indicating an expansion in the bank’s deposit base. Net loans and advances also increased by 23 per cent to Sh56.5 billion as lending activity expanded.
The bank further reported an improvement in its non-performing loan ratio, which declined to 16.9 per cent from 32.3 per cent a year earlier.
The reduction points to an improvement in the proportion of loans classified as non-performing, although the ratio remains an important measure of credit risk for the lender.
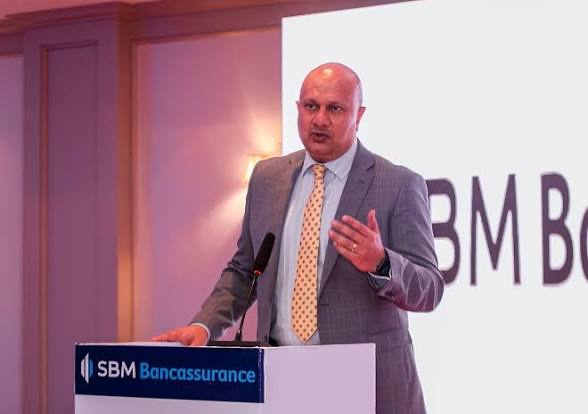
SBM Bank Kenya Chief Executive Bhartesh Shah attributed the performance to stronger credit discipline, deeper customer relationships and diversified income streams.
Credit management remains a significant consideration for lenders because unpaid or overdue loans can affect earnings, liquidity and the capacity to extend credit to customers.
A decline in the non-performing loan ratio can help reduce pressure associated with problem loans, depending on the underlying quality and composition of the loan portfolio.
The increase in customer deposits also provides the bank with a larger pool of funds to support its banking operations.
Growth in deposits and lending can indicate expanding customer activity, although sustainable performance also depends on maintaining sound risk controls and managing operating costs.
The latest results place the lender among financial institutions reporting improved earnings during the period.
Its stronger income and operating profit figures, alongside growth in deposits and loans, highlight the main drivers of its performance.
However, the bank’s continued progress will depend on sustaining income growth, managing credit risk and maintaining customer confidence as it expands its lending and deposit-taking activities.