China’s economy grew by 4.5% year-on-year in the third quarter of 2026, accelerating from 4.3% in the previous quarter as strong exports of technology products and manufacturing output supported growth despite weak domestic demand and continuing pressure on the property sector. Data released by China’s National Bureau of Statistics on Monday, October 19, showed the recovery exceeded economists’ expectations and kept the country within reach of its annual growth target.
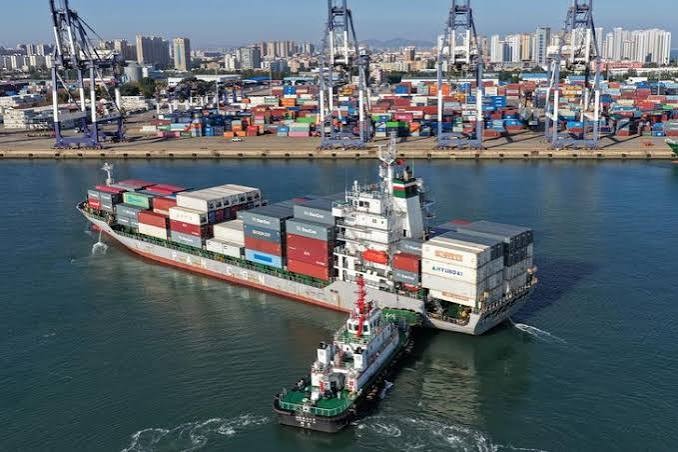
The July-to-September performance was supported by overseas demand for Chinese goods, particularly electronics and components linked to the global artificial intelligence boom. Manufacturers have benefited from demand for technology-related products, helping exports remain a key driver of economic activity as domestic investment struggles to recover.
China’s gross domestic product (GDP) expanded by 4.6% during the first nine months of 2026, according to the official figures. The government has set a full-year growth target of between 4.5% and 5%, making export performance an important factor in determining whether the economy achieves its objective.
Industrial production rose by 5.5% in September, while retail sales increased by 1.1%, reflecting continued weakness in household spending despite government measures intended to encourage purchases. Fixed-asset investment declined by 7.2%, highlighting the difficulties facing businesses and local governments as they navigate uncertain demand and financing constraints.
The property market remains another major obstacle to a broader recovery. Falling home prices and weak investment have weighed on confidence among households and businesses, limiting the extent to which domestic consumption can offset external economic pressures.
Beijing has increasingly directed resources towards advanced manufacturing and strategic industries as it seeks to strengthen technological capabilities and reduce reliance on traditional growth drivers. However, the strategy has contributed to an uneven recovery, with export-oriented industries performing more strongly than parts of the domestic economy.
China’s expanding trade surplus has also increased tensions with major trading partners, particularly the European Union, where concerns about competition from Chinese manufacturers have prompted discussions over trade restrictions and import controls.
The outlook remains uncertain as demand for artificial intelligence infrastructure evolves and trade disputes threaten access to overseas markets. A slowdown in technology investment could reduce demand for Chinese electronics and industrial components, putting additional pressure on exporters.
Policymakers are therefore expected to face growing pressure to strengthen household consumption, stabilise the property sector and support private investment. The next economic indicators and policy announcements will offer further evidence of whether China can sustain export-led growth while addressing weaknesses in its domestic economy.